The VA home loan benefit makes 0% down purchases possible for eligible service members, veterans, and military spouses. VA loan entitlement is the mechanism behind that benefit. It determines how much the VA guarantees to your lender and affects when and how you can rent out a home purchased with a VA loan.
Whether PCS orders have arrived, you are heading overseas, or your family is ready for a larger home, the occupancy-to-rental rules matter. Understanding those rules can help you protect your VA loan benefit as your housing needs change.
What Is VA Loan Entitlement?
VA loan entitlement is the dollar amount the U.S. Department of Veterans Affairs guarantees to your lender if you default on your mortgage.
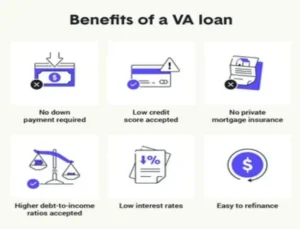
As a government loan guarantee , it can eliminate the need for the down payment and private mortgage insurance typically associated with conventional loans. If you default, the VA covers the guaranteed portion for the lender.
VA loan entitlement can appear in five forms, each relating to a different stage of VA loan use:
- Basic entitlement: $36,000, the historical baseline associated with loans up to $144,000.
- Bonus entitlement, or second-tier entitlement: Additional coverage for loans above $144,000, calculated as 25% of the applicable county loan limit minus $36,000.
- Full entitlement: Available when entitlement is entirely unused or has been fully restored. Borrowers with full entitlement are not subject to a VA loan limit, provided they qualify financially.
- Partial entitlement: The entitlement remaining after a previous VA loan has been used and the entitlement tied to that loan has not been restored.
- Restored entitlement: Basic or bonus entitlement regained after the property is sold and the VA loan is paid off, or through an eligible one-time restoration.
Your Certificate of Eligibility (COE) is the VA-issued document showing your current entitlement amount, eligibility category, and previous VA loan usage.
Lenders require a COE when processing a VA loan application. You can request yours through VA.gov or ask your lender to retrieve it electronically.
County loan limits can affect the amount of bonus entitlement available when you have partial entitlement. FHFA publishes current conforming loan limits by county , so check the applicable limit for your next duty station before calculating your available entitlement.
The Short Answer: Can You Rent Out a Home Purchased With a VA Loan?
Yes, you can rent out a home purchased with a VA loan after meeting the applicable occupancy requirements.
You cannot use a VA loan to purchase a property with the intention of immediately operating it solely as a rental.
The VA home loan benefit is intended for primary residences , not investment properties.
A permitted path is to purchase the property with a genuine intent to occupy it as your primary residence, establish occupancy, and later convert it into a rental because your circumstances change. Common examples include PCS orders, deployment, relocation, or changing family needs.
| Situation | Can You Rent? | Condition |
|---|---|---|
| Just bought the home and have not moved in | No | Initial occupancy requirements must first be satisfied |
| Lived there for 6 months and received PCS orders | Yes | Changed circumstances may support rental conversion; retain your PCS documentation |
| Lived there for 2 years and are upgrading to another home | Yes | Primary occupancy has already been established |
| Bought a multi-unit property and live in one unit | Yes, for the other units | Non-owner-occupied units may be rented while you occupy one unit as your primary residence |
| Deployed before closing | Conditional | Spouse occupancy or lender-approved occupancy arrangements may apply |
Occupancy timing and bona fide intent are central to these scenarios. Military-specific circumstances can also affect how the occupancy requirement is applied.
The 12-Month Occupancy Rule: What It Really Means
The commonly referenced 12-month occupancy period functions as a guideline rather than a blanket federal rule requiring every VA borrower to remain in the property for exactly one year before moving.
The key issue is whether you purchased the property with a genuine intention to use it as your primary residence.
The General Rule: 12 Months of Primary Residence
A 12-month period is commonly used as a benchmark when evaluating whether a borrower genuinely intended to occupy the home.
- Not a universal statutory requirement: VA occupancy rules focus on bona fide intent and reasonable occupancy rather than one fixed timeline that applies identically to every situation.
- Fewer than 12 months: Changed circumstances may need to be documented, particularly if the home is converted to a rental soon after purchase.
- Lender overlays: Individual lenders may impose requirements beyond VA minimums. Review your loan documents and speak with your lender before converting the property.
The PCS Exception: When Military Orders Change Your Housing Plans
PCS orders can create a legitimate change in circumstances after you purchase and occupy a VA-financed home.
The important distinction is intent. If you genuinely purchased the property as your primary residence and later received orders requiring you to relocate, the circumstances behind your occupancy have changed.
- Retain your PCS orders: Keep both physical and digital copies in your loan file.
- Document your original occupancy: Maintain evidence showing that the home was purchased and occupied as your primary residence.
- Keep records of the changed circumstances: Your PCS orders help demonstrate why the property was later converted into a rental.
- Speak with your lender: Confirm whether your loan contains additional lender-specific requirements before listing the property.
Navigating a PCS while managing an existing VA loan? MilHousing PCS Mentors can connect you with advisors familiar with the military relocation process.
Deployment and Temporary Duty (TDY) Exceptions
Deployment can also affect occupancy. For an active duty service member who is deployed, a spouse’s occupancy may satisfy the primary residence requirement when the property remains the family’s primary home.
- Married and deployed: A spouse may occupy the property as the family’s primary residence. Keep deployment orders with your records.
- Single and deployed: If deployment occurs before closing, coordinate with your lender and document your intended occupancy arrangements.
- TDY: A short-term temporary duty assignment typically does not mean that you have abandoned the property as your primary residence.
Job Relocation as a Changed Circumstance
A civilian job relocation can also change your housing circumstances after purchasing a VA-financed home.
Examples may include moving for a defense contractor position, federal agency transfer, or private-sector employment.
Useful documentation can include:
- Job offer letter: An official letter confirming the new position and location.
- Acceptance confirmation: A signed employment agreement or other evidence that you accepted the position.
- Proof of relocation: Documentation connecting you with the new location.
Check with your lender regarding the documentation required for your specific loan.
Family Size Changes
A significant change in family size may also affect whether your existing property continues to meet your housing needs.
- Birth: Keep relevant documentation with your records.
- Adoption: Retain adoption or finalization documents.
- Other family changes: Keep documentation supporting the circumstances and confirm lender requirements when necessary.
VA Entitlement: What Happens When You Rent Out Your Home?
Your Entitlement Stays Tied to the Home Unless You Restore It
When a VA-financed home becomes a rental, the entitlement associated with that loan generally remains tied to the property while the VA loan remains outstanding.
This can reduce the entitlement available for another VA-financed purchase.
| Scenario | Entitlement Status | Potential Effect on Next VA Loan |
|---|---|---|
| Keep the home as a rental without restoring entitlement | Remains tied to the current property | You may have partial entitlement remaining |
| Sell the home and pay off the VA loan | Entitlement can be restored after payoff | Full entitlement may become available again |
| Qualified veteran assumes the VA loan with substitution of entitlement | Entitlement may be released through the approved assumption process | Can restore purchasing flexibility |
| Pay off the VA loan while retaining the property and use one-time restoration | Entitlement may be restored under the one-time restoration provision | Full entitlement may become available again |
For many PCSing service members who want their entitlement restored, the straightforward route is to sell the property, pay off the VA loan, and request restoration.
Keeping the property as a rental can still be an option, but you need to understand how much entitlement remains available before purchasing at the next duty station.
How to Calculate Your Remaining Entitlement
When you have partial entitlement, the calculation depends on the applicable conforming loan limit and the amount of VA entitlement already charged to your existing loan.
Your remaining entitlement can affect how much you can borrow on another VA loan without making a down payment.
Consider this example:
- You purchased a home for $300,000 using a VA loan.
- $75,000 of entitlement was charged to that loan.
- You are now PCSing and want to keep the property as a rental.
- You also want to purchase a home at your next duty station.
The general calculation follows this sequence:
- Identify the applicable county conforming loan limit.
- Calculate 25% of that limit.
- Subtract the entitlement already charged to your existing VA loan.
- Use the remaining guaranty to determine how much additional VA-backed borrowing may be available without a down payment.
Because loan limits change over time and can vary by location, check the current FHFA conforming loan limits and your current COE before relying on any calculation.
Before purchasing at your next duty station, consider a Military Home Buying Assessment to review your purchasing situation and location-specific considerations.
The One-Time Restoration Rule
One-time restoration may allow you to restore entitlement after the VA loan has been paid in full even when you retain ownership of the property.
- Eligibility: The VA-backed loan on the retained property must generally be paid in full.
- Frequency: The special restoration provision is generally available once.
- Process: VA Form 26-1880 is used when requesting restoration of entitlement.
- Outcome: Approved restoration can make previously used entitlement available again.
Using Rental Income to Qualify for Your Next VA Loan
Rental income from your existing property may help when qualifying for another mortgage, but lenders apply underwriting requirements before counting that income.
A commonly used calculation counts 75% of documented gross rent, allowing the remaining 25% for vacancy and operating expenses.
The 75% Rule: How Lenders Calculate Rental Income
Under a 75% rental-income calculation, a property generating $2,000 per month in gross rent would produce $1,500 per month in countable rental income.
| Gross Rental Income | 75% Amount | Documentation Consideration |
|---|---|---|
| $1,500/month | $1,125 | Signed lease and lender documentation may be required |
| $2,000/month | $1,500 | Signed lease agreement may be required |
| $2,500/month | $1,875 | Reserve or additional underwriting requirements may apply |
| $3,000/month | $2,250 | Established rental history and tax documentation may strengthen the file |
Documentation Required for Rental Income
- Signed lease agreement: Shows the monthly rent amount and lease term.
- Security deposit documentation: May help establish that a tenant has committed to the property.
- Rental payment history: Existing landlords may be asked to provide records demonstrating rental receipts.
- Tax returns showing rental income: Schedule E can document existing rental activity.
- Market rent documentation or appraisal: A lender may request market-rent evidence when established rental history is unavailable.
Reserve Requirements for Rental Properties
Some lenders may require cash reserves when rental income is being used to qualify for another mortgage.
A lender overlay may require several months of PITI, meaning principal, interest, taxes, and insurance, for one or both properties.
Multi-Unit Properties: Renting the Other Units
VA loans can be used for eligible 2-to-4-unit residential properties when the borrower occupies one unit as a primary residence.
Buying a Duplex, Triplex, or Quadplex With a VA Loan
- You must occupy one unit: The property must meet applicable owner-occupancy requirements.
- Other units can be rented: The non-owner-occupied units can generate rental income while you live in the property.
- Rental income may help with qualification: Subject to lender underwriting requirements, projected or established rent from the other units may be considered.
Example: The Live-In Landlord Strategy
Consider a $400,000 quadplex where three units rent for $1,200 per month each.
- You live in Unit A.
- Units B, C, and D produce $3,600 in total gross monthly rent.
- At a 75% calculation, $2,700 per month may potentially be considered by the lender, subject to underwriting requirements.
- If you later PCS and convert Unit A into a rental after satisfying applicable VA and lender requirements, the property could eventually become fully tenant occupied.
PCS Orders and VA Loans: Your Action Plan
PCS orders can trigger several housing decisions at once. You may need to decide whether to sell or rent the current property, determine what happens to your VA entitlement, prepare the home for tenants, and evaluate purchasing options at the next duty station.
Timeline: What to Do When PCS Orders Arrive
| Timeframe | Action |
|---|---|
| Day 1 | Save physical and digital copies of your PCS orders |
| Week 1 | Review your mortgage and contact your lender if clarification about occupancy or loan requirements is needed |
| Week 2 | Interview property managers if you plan to rent and will not self-manage |
| Week 4 | Prepare and list the property, coordinating the listing with your confirmed move-out timeline |
| Week 8 | Complete your move and transition the home to the tenant if the property has been rented |
| Week 12 | Organize rental documentation and discuss how the income may affect qualification for housing at your next duty station |
Can My Spouse Handle Occupancy While I’m Deployed?
Yes, spouse occupancy can satisfy VA occupancy requirements in qualifying circumstances when an active duty service member is deployed.
The property must continue to function as the family’s primary residence. Keep your deployment orders and related documentation with your loan records.
What If I’m Stationed Overseas and Want to Rent My VA Home?
An overseas assignment does not automatically prevent a property from being converted into a rental after legitimate primary occupancy has been established and applicable loan requirements have been met.
For service members living overseas, a U.S.-based property manager can handle:
- Tenant screening
- Lease administration
- Maintenance coordination
- Rent collection
- Local property issues
Dual-Military Couples: VA Loan Rules When Both Spouses Serve
- One spouse PCSs while the other remains: If the non-PCSing spouse continues occupying the property as a primary residence, immediate rental conversion may not be necessary.
- Both spouses PCS: Keep both sets of orders and document the circumstances surrounding the relocation.
- Co-borrower considerations: How the loan and entitlement are structured can affect future VA borrowing.
- Separate VA entitlement: When both spouses independently qualify for VA loan benefits, their individual entitlement positions can affect future financing options.
Becoming an Accidental Landlord: What Changes Immediately
An accidental landlord is a homeowner who converts a primary residence into a rental because circumstances such as PCS orders, deployment, relocation, or changing housing needs make selling or continuing to occupy the property impractical.
- Insurance: Speak with your insurer about landlord or dwelling coverage before the tenant moves in.
- Tax classification: Rental income generally needs to be reported, and eligible rental expenses may be deductible using IRS Schedule E .
- Lease terms: Understand the Servicemembers Civil Relief Act when renting to military tenants.
- Entitlement strategy: Determine whether the VA entitlement tied to the existing property will remain in use or be restored.
- Property management: If you are PCSing far from the property, determine who will manage the home before it is listed.
Cross-Border Considerations: Renting Your U.S. VA Home While Living in Canada
U.S. veterans who live in Canada while owning a U.S. rental property can face tax and reporting considerations in both countries.
Cross-border taxation is highly fact-specific, so work with a professional familiar with both U.S. and Canadian tax rules before making decisions based on residency or rental income.
Tax Implications for U.S. Veterans Living in Canada
- U.S. rental income reporting: Income and eligible expenses associated with U.S. residential rental property may need to be reported using Form 1040, Schedule E .
- Canadian reporting: Canadian residents may also have reporting obligations related to foreign-sourced rental income.
- Residency and withholding rules: Applicable rules depend on residency, ownership structure, source of income, and tax status.
- Foreign tax credits: The U.S.-Canada tax treaty and foreign tax credit mechanisms can affect how tax paid in one country is treated in the other.
- Depreciation and sale consequences: Renting a former residence can affect depreciation, capital gains calculations, and potential depreciation recapture.
Currency Exchange and Rental Income
- Track applicable USD/CAD exchange rates for rental transactions.
- Maintain clear records of rent and property expenses in their original currency.
- Consider a USD-denominated account for U.S. rental activity.
- Work with a cross-border accountant familiar with both U.S. and Canadian rental-property reporting.
Property Management From Abroad
A U.S.-based property manager can manage day-to-day rental operations while you live outside the country.
- Military tenant requirements: A manager familiar with military tenants should understand applicable SCRA protections.
- Online rent collection: Electronic payments can make rental recordkeeping easier.
- Tax documentation: Make sure the property manager and your tax advisor understand your residency and ownership status.
Step-by-Step Guide: How to Rent Out Your VA Home Legally
Renting out a VA-financed home requires more than finding a tenant. Work through the following steps before converting your property from a primary residence into a rental.
1. Verify That You Have Met the Occupancy Requirements
Confirm that you originally purchased and occupied the property in accordance with VA and lender requirements.
If you are moving sooner than expected because of PCS orders, deployment, employment relocation, or another changed circumstance, keep supporting documentation.
2. Review Your Loan Documents
Check for lender-specific requirements or overlays beyond VA minimum standards.
If anything about rental conversion or occupancy is unclear, contact your lender before listing the property.
3. Check Your Entitlement Status
Obtain your COE through VA.gov and confirm how much entitlement is currently tied to the existing property.
If you expect to purchase another home using VA financing, understanding your remaining entitlement is critical.
4. Decide on an Entitlement Strategy
Determine whether you intend to:
- Keep the existing VA loan and use remaining entitlement for another purchase.
- Sell the property and request restoration.
- Pay off the existing VA loan while retaining the property and determine whether one-time restoration applies.
Your choice can affect the amount available for your next VA-financed purchase.
5. Find a Qualified Property Manager
If you are PCSing far from the property or do not want to manage the rental yourself, identify and vet qualified property managers before listing the home.
Look at tenant screening procedures, maintenance processes, fee structures, communication standards, military-tenant experience, and local market knowledge.
Need help finding property management near your home?
Share the property’s location and we’ll help identify an appropriate professional in our network.
Request Property Management Help✓ For homeowners who need trusted local property-management support.
- ✓ Remote-friendly support
- ✓ Qualified local professionals
- ✓ Simple next steps
6. Screen Tenants and Prepare the Lease
Screen prospective tenants carefully and use a lease that complies with applicable federal, state, and local requirements.
If military tenants are involved, understand their protections under the Servicemembers Civil Relief Act .
7. Document Everything
Maintain organized records including:
- Signed lease agreements
- Security deposit documentation
- Rental payments
- Tenant correspondence
- PCS or deployment orders
- Property-management agreements
- Repair and maintenance expenses
These records can become important for tax reporting, landlord compliance, and future mortgage underwriting.
8. Update Your Insurance
Tell your insurance provider that the property will become tenant occupied.
Discuss whether landlord insurance, dwelling coverage, liability coverage, or other adjustments are necessary before the tenant moves in.
9. Plan for Rental Income Taxes
Rental income can create new tax and recordkeeping obligations.
Track relevant expenses such as:
- Repairs
- Property-management fees
- Mortgage interest
- Insurance
- Eligible operating expenses
- Depreciation
Review IRS Schedule E and IRS Publication 527 , and consult a qualified tax professional regarding your specific situation.
VA Loan Rental FAQ
Can I rent my home that has a VA loan?
Yes. A VA-financed primary residence can later be converted into a rental after legitimate occupancy has been established and applicable VA and lender requirements have been satisfied.
PCS orders, deployment, job relocation, and changing family circumstances can affect the timing and documentation involved.
How long before I can rent my VA home?
There is no one timeline that should be applied blindly to every VA borrower.
The key considerations are your genuine intent to occupy the property when it was purchased, whether legitimate occupancy was established, your reason for later moving, and any requirements imposed by your lender.
Why does Dave Ramsey not recommend a VA loan?
Dave Ramsey has criticized aspects of VA loans, including the VA funding fee and the possibility of borrowers purchasing homes without a down payment.
For eligible military borrowers, VA financing can provide advantages including:
- No required down payment in many qualifying situations
- No private mortgage insurance
- Competitive financing terms
- Reusable VA loan entitlement
- Options for eligible military borrowers whose housing needs change after PCS orders
Do I have to refinance before I can rent out my VA home?
No. A VA-financed property can generally be converted into a rental without refinancing solely because it is becoming tenant occupied, provided applicable occupancy and loan requirements have been satisfied.
Can I use a VA loan to buy a rental property?
Not as a non-owner-occupied investment property from the start.
VA purchase loans are designed to finance primary residences. An eligible borrower can purchase a qualifying property as a primary residence and later convert it into a rental after satisfying applicable occupancy requirements.
For related housing planning, review our guide to BAH basics .
How do I restore my VA entitlement after renting?
One common route is selling the home , paying the VA loan in full, and requesting restoration of entitlement.
In certain circumstances, one-time restoration may also be available when the VA loan has been paid in full but the veteran retains ownership of the property.
VA Form 26-1880 is used in connection with requesting a Certificate of Eligibility and restoration of entitlement.
What is bonus entitlement?
Bonus entitlement, also called second-tier entitlement, refers to additional VA guaranty beyond the historical $36,000 basic entitlement.
Can my spouse occupy the home for me while I’m deployed?
Yes, spouse occupancy can satisfy VA occupancy requirements in qualifying circumstances for an active duty service member who is deployed.
Keep deployment orders and related records with your loan documentation, and confirm any lender-specific requirements before closing.
Next Steps
VA entitlement and rental conversion should be handled as a sequence:
- Confirm that your original occupancy requirements were satisfied.
- Document PCS orders, deployment, or another relevant change in circumstances.
- Check how much VA entitlement remains available.
- Determine whether you will sell, keep, or pay off the current property.
- Prepare the property for rental if you are keeping it.
- Organize rental-income documentation.
- Evaluate your housing and financing options at the next duty station.
For a broader look at your options after a military move, review our guide to military housing options , including on-base family housing and barracks.
Ready to transition your VA home into a rental? MilHousing’s Accidental Landlord resources can help you think through the responsibilities that come with maintaining a property after a PCS move.
Managing the PCS itself? MilHousing PCS Mentors can connect you with people familiar with the relocation process.
Purchasing at your new duty station with remaining VA entitlement? Consider a Military Home Buying Assessment to review your purchasing situation before making an offer.
If military housing is part of your next move, read our complete guide to what furniture and appliances military housing includes .